Developing Guidelines of Risk Management of Budget base of Lokapala-Dhamma in Bannasae School under the Nakhon Si Thammarat Primary Educational Service Area Office 2
Article Sidebar
Main Article Content
Abstract
This research article aims to Study: study the conditions of budget risk management; 2) examine the guidelines for budget risk management based on the World-Protecting Principles; and 3) propose and evaluate the guidelines for budget risk management based on the World-Protecting Principles. This study employed a qualitative research methodology. Data were collected through in-depth interviews with 19 participants involved in budget administration. In addition, five key informants participated in a focus group discussion. The participants were selected through purposive sampling, including seven experts/monks and qualified persons. Data were analyzed using inductive analysis.
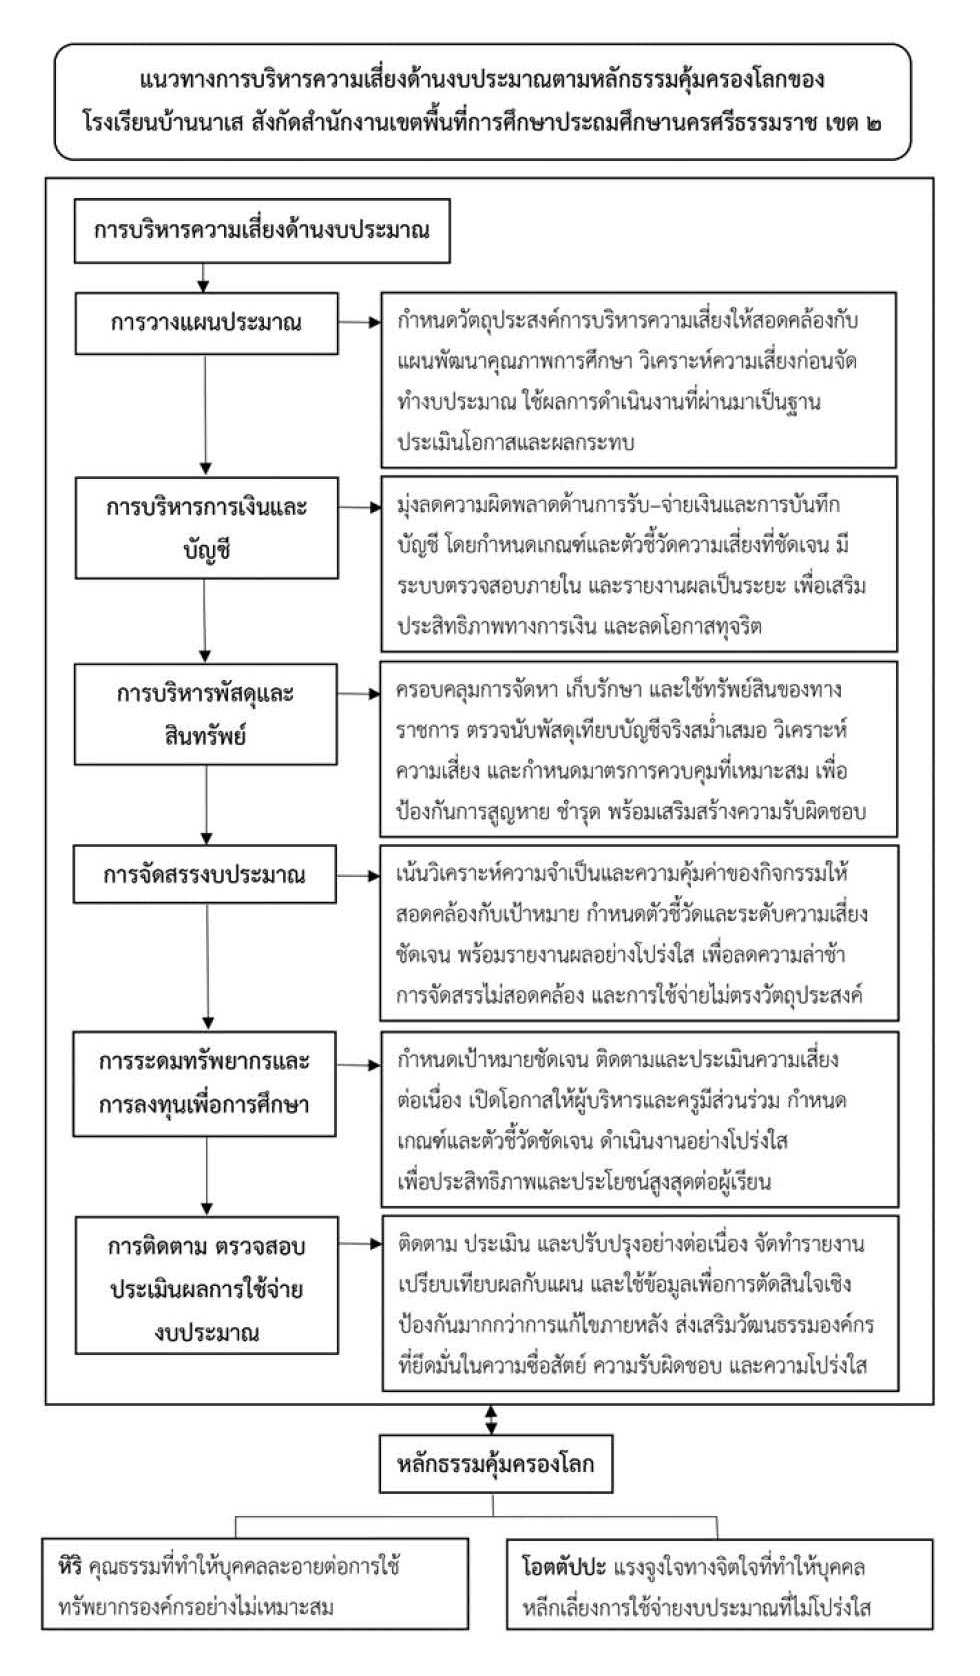
The research results were found as follows: 1) the current state of budget risk management in the educational institution is systematically implemented, aligned with the vision, policies, educational development plans, and annual action plans. Objectives are established based on empirical data and past performance. Administrators, teachers, staff, and school committee members are involved in identifying and assessing risks. A comprehensive and transparent risk management plan with clear indicators is developed. However, limitations were found in terms of time constraints, workload, unsystematic data management, unequal levels of understanding, and insufficient communication. These issues result in incomplete and untimely data analysis and reporting, thereby affecting decision-making efficiency. 2) The guidelines for budget risk management based on the Lokapāla Dhamma, particularly the integration of Hiri (moral shame) and Ottappa (moral fear), help strengthen ethical awareness alongside internal control systems. This contributes to transparent budget management, reduces errors and corruption, and promotes the efficient use of resources for sustainable educational quality development. 3) The results of the presentation and evaluation of the proposed guidelines, as assessed by experts, indicated that they are appropriate, feasible, and beneficial.
Downloads
Article Details

This work is licensed under a Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International License.
References
ก้องเกียรติ เติมเกษมศานต์. (ม.ป.ป.). โลกปาลธรรม. [ออนไลน์]. แหล่งที่มา: https://www.gotoknow.org/posts/229358 [14 สิงหาคม 2567].
กระทรวงศึกษาธิการ. (2542). พระราชบัญญัติการศึกษาแห่งชาติ พุทธศักราช 2542. ราชกิจจานุเบกษา, 116 (74ก), 24.
จันทร์จิรา โชติพิบูลย์ และสุรางคนา มัณยานนท์. (2565). การบริหารงานด้านงบประมาณโรงเรียนในสังกัดสำนักงานเขตพื้นที่การศึกษาประถมศึกษาบึงกาฬ. วารสารวิทยาการจัดการ มหาวิทยาลัยราชภัฏสกลนคร, 2(1): 11-17.
นัทพงศ์ หมิแหละหมัน. (2564). แนวทางการบริหารความเสี่ยงด้านงบประมาณของสถานศึกษายุคดิจิทัล สังกัดสำนักงานเขตพื้นที่การศึกษามัธยมศึกษาอุดรธานี. วารสารวิชาการ สถาบันเทคโนโลยีแห่งสุวรรณภูมิ, 7(1): 588-602.
นิตยา กรุพิมาย. (2567). แนวทางการบริหารความเสี่ยงด้านงบประมาณของสถานศึกษายุคดิจิทัล สังกัดสำนักงานเขตพื้นที่การศึกษามัธยมศึกษาอุดรธานี. วารสาร มจร อุบลปริทรรศน์, 9(3): 75-98.
บุศราคัม คำปลิว. (2568). การพัฒนาแนวทางการบริหารความเสี่ยงด้านงานงบประมาณในสถานศึกษา สังกัดสำนักงานเขตพื้นที่การศึกษามัธยมศึกษามหาสารคาม. วารสารการบริหารการศึกษา มมร. วิทยาเขตร้อยเอ็ด, 1(3): 77-80.
พิษณุ หอมสมบัติ. (2565). พุทธธรรมคุ้มครองโลก: การป้องกันการทุจริตอย่างยั่งยืน. วารสาร มจร อุบลปริทรรศน์, 7(2): 67-79.
มัทนียา เพ็ชรนอก. (2563). การพัฒนาแนวทางการบริหารความเสี่ยงด้านงานงบประมาณในโรงเรียนมัธยมศึกษา สังกัดสำนักงานเขตพื้นที่การศึกษามัธยมศึกษา เขต 25. วิทยานิพนธ์การศึกษามหาบัณฑิต, บัณฑิตวิทยาลัย, มหาวิทยาลัยมหาสารคาม.
วิภาดา ศิริวงศ์. (2566). แนวทางการบริหารความเสี่ยงด้านงานงบประมาณของโรงเรียนในสังกัดสำนักงานเขตพื้นที่การศึกษาประถมศึกษานครราชสีมา เขต 4. วารสารครุศาสตร์อีสาน, 25(2):18- 45.
ศุภกิจ ภูโอบ. (2560). การบริหารงบประมาณในสถานศึกษาขั้นพื้นฐานตามหลักธรรมคุ้มครองโลกสังกัดสำนักงานเขตพื้นที่การศึกษาประถมศึกษานครราชสีมา เขต 5. วิทยานิพนธ์พุทธศาสตรมหาบัณฑิต, บัณฑิตวิทยาลัย, มหาวิทยาลัยมหาจุฬาลงกรณราชวิทยาลัย.
สำนักปฏิรูปการศึกษา กระทรวงศึกษาธิการ. (2545). ข้อเสนอแนะทางการบริหารจัดการศึกษาในสถานศึกษา กรุงเทพมหานคร. กรุงเทพฯ: โรงพิมพ์ชุมชนสหกรณ์การเกษตรแห่งประเทศไทย.
อุษณา ภัทรมนตรี. (2552). การตรวจสอบภายในสมัยใหม่: แนวคิดและกรณีศึกษา. กรุงเทพฯ: จามจุรีโปรดักท์.
